Mortgage Fraud Defence Solicitors
One letter from your lender can turn a mortgage into a criminal case; Holborn Adams are the mortgage fraud defence solicitors in London who act at once. The charge is fraud by false representation under section 2 of the Fraud Act 2006, carrying up to 10 years in prison. Early advice is critical; call our mortgage fraud solicitors 24/7.

Act Early in a Mortgage Fraud Investigation
Holborn Adams is a specialist criminal defence firm, and our fraud solicitors sit at the core of the practice. We have represented countless clients accused of mortgage fraud, from high-value property purchases and false income declarations to professional misconduct. Our mortgage fraud solicitors in England and Wales act wherever the lender, the police, or the court sits. Legal 500 recognises our directors, and its guide points readers to the sharpest legal minds in the country.
Timing decides more than most people expect. Ring us the day a lender’s letter lands, and every option stays open; ring after a police interview, and the choices narrow. That is why we move fast, from the first sign of an investigation through to any court appearance.
Our approach centres on early resolution, discreet crisis management, and, where appropriate, voluntary disclosure that reduces your legal risk. We deal directly with lenders, investigators, and enforcement bodies to lower the temperature, and we bring in financial specialists to strengthen your defence. Our mortgage fraud lawyers also handle the knock-on problems, such as contesting restraint orders and securing more flexible bail conditions, all aimed at keeping disruption to your life small.
As a private firm, we defend clients for a fixed fee. That model buys time and attention for your case, and you will feel the difference in the level of care you receive.
What Is Mortgage Fraud?
Giving a lender false or misleading information, or concealing something that matters, to win a mortgage or better terms is a crime. A rounded-up salary, a debt left off the form, or a family gift described as a deposit can each bring an allegation of mortgage application fraud. Prosecutors usually charge fraud by false representation under section 2 of the Fraud Act 2006 or the withholding of information you have a duty to disclose under section 3. Both carry a maximum of 10 years in prison. The offence is committed as soon as the statement is made. Repaying the loan in full can soften the sentence, yet the charge remains available.
Types of Mortgage and Property Fraud We Defend
Lenders, brokers, and the police see these patterns daily, so each allegation of mortgage loan fraud arrives with a ready-made label. Our job is to test whether the label fits you. Cases we defend include:
- Misleading or false applications, including inflated income and false payslips
- Undisclosed debts or other liabilities
- Undeclared funds used for a deposit, including a “gifted deposit” that is really a loan
- Buy-to-let purchases made on a residential mortgage
- Inflated property valuations used to secure a larger loan
- Identity fraud, including applications made in another person’s name
- Several mortgages secured on one property, each concealed from the next lender
- Misconduct by mortgage brokers, conveyancers, or valuers, such as submitting false documents or coaching clients to lie
We also defend wider property fraud allegations, such as false documents in a property sale or a purchase made in another person’s name.
Most of these allegations are charged as fraud by false representation under section 2 of the Fraud Act 2006, with a maximum of 10 years in prison. Forged payslips or valuations can add a forgery charge under section 1 of the Forgery and Counterfeiting Act 1981, also carrying up to 10 years. Our money laundering solicitors defend related allegations under sections 327 to 329 of the Proceeds of Crime Act 2002 (POCA), which carry up to 14 years. We also defend insurance fraud, charged under section 2 of the Fraud Act 2006, with the same 10-year maximum.
Who Investigates Mortgage Fraud?
Lenders’ fraud teams and the police lead these investigations, with specialist regional fraud teams or the National Crime Agency joining larger or linked cases. Your lender’s fraud team usually spots the problem first, and a report through Action Fraud often follows. The largest cases need serious fraud solicitors from day one. Lenders may also record a fraud marker against your name with Cifas, the fraud-prevention body. That marker typically stays on file for six years and can affect future credit, even when the matter ends before charge.
What Happens If You Are Accused of Mortgage Fraud?
A letter from your lender or a call from the police comes first, then an interview under caution, a charging decision, and, after a conviction, confiscation proceedings. Your replies can shape the whole case. Honest and consistent answers are critical, so take advice before you sit down. The Crown Prosecution Service (CPS) makes the charging decision. After a conviction, POCA allows the court to make a confiscation order, which can reach the property itself. The court looks at the benefit you gained and the assets available to pay it. Early advice on confiscation and asset restraint limits the damage.
A letter already in your hand? Keep every document: the application, payslips, bank statements, and emails with your broker. Speak to a solicitor before you reply to anyone. Each stage offers a chance to change the direction of the case. Use it.
How Our Mortgage Fraud Solicitors Defend You
Dishonesty decides these cases, so we press there first. Prosecutors must prove it against each person, and a broker’s error or a misread form is a different matter from a plan to deceive. Our aim is simple: an honest explanation for every figure. We test the paperwork and the valuations line by line, and we bring in forensic accountants to rebuild the financial picture the Crown relies on. We prepare you for every question before you answer it, so your account stays consistent from the first interview to the last. Before any charge, pre-charge representation to the police and the lender can close a file early. Should a charge arrive, the same groundwork carries into court.
Brokers, Conveyancers and Other Professionals
Professionals can face criminal and regulatory action at once, with the Financial Conduct Authority (FCA) or the Solicitors Regulation Authority (SRA) investigating alongside the police. We coordinate both tracks as a single defence; our page on regulatory offences explains how.
Facing a lender’s letter or a police call? Phone Holborn Adams on 020 3870 2249, any hour, any day. Your call is confidential.
Reviewed by Rozhin Tajermanshadi, Head of Crime & Regulatory, Holborn Adams. Last reviewed 18 November 2026.
Nationwide Support
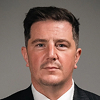
We take on clients across the UK
We have offices spread all across the UK (and even beyond!). We can represent you no matter where you are in the UK.
What we can offer
Extensive experience from successful cases.
Optional visits to your home to discuss case details.
Remote communications to save you travel time.
Ability to work to tight timescales to match the pace of the case.
Transparent pricing with fixed fees*
Our process
Our Process
Enquiry Call with a Legal Expert
Call our mortgage fraud solicitors for a confidential discussion about your situation. We listen, outline your options, and give a clear estimate of costs.
Case Review and Approval
We look at the details and set out exactly what the work will cost. You decide when to go ahead, and we start on your defence straight away.
Strategy development
We work alongside financial experts and property specialists to challenge the claims, question the evidence and push for an early resolution.
Representation
From interviews to inquiries from lenders to full proceedings, we handle communications on your behalf and defend your interests at every stage.


Respected and trusted
As proud members of the UK’s largest legal sector governing bodies, we are a team you can put your full trust in. We adhere to strict industry regulations, so you can be confident your case is in safe hands.
Our legal services
How Our Mortgage Fraud Solicitors Can Help You
Every mortgage fraud investigation follows its own course. Our team applies close analysis and early intervention to pursue the strongest result available.

Apply For Varied Bail Conditions
Bail conditions and restraint orders can freeze your finances long before any confiscation order. We apply to vary them, seeking room to work and live normally during the investigation.

Create A Defence Strategy
We work with forensic accountants and property experts, testing every claim of inflated income against the paperwork. Gaps in the evidence become the foundation of your defence.

Reputation management
A Cifas fraud marker or a whisper at work can damage your career before any charge. We manage the message quietly, protecting your standing with employers, lenders, and professional bodies.

Attend Interviews
An interview under caution shapes everything that follows. We sit beside you, explain your rights, and prepare every answer, so each word you give supports your defence.

Early Resolution with Police
A weak file or a procedural flaw can end an investigation quickly. We press the police and your lender for a decision to drop the case before any charge.
Convincing The CPS Not to Proceed
Should a charge follow, we put detailed representations to the CPS on the evidence and the Fraud Act 2006 test of dishonesty, pressing for the case to stop before trial.
Independent reviews
Explore our Trustpilot reviews to see what our customers have to say about their experiences with us!

No other firm came to my aid in the maximum time of need.
I had an urgent situation on a Sunday afternoon bank holiday and two different attorneys got involved immediately, with compassion, and outstanding assistance.

I’ve turned to Holborn Adams’ expertise for some of the most important matters in my life.
I’ve had the privilege of working with Holborn Adams Solicitors, and in particular, Adam Rasul, who has provided exceptional legal services and advice throughout my boxing career and beyond.

Experienced, empathetic support in a difficult situation.
Throughout the whole process I felt I had support from Lara and the team.

The professionalism, attention to detail, and depth of legal knowledge are second to none.
I would not hesitate to recommend Adam and his team to anyone looking for first-class legal representation there really is no other firm you need to look for – case closed.

Hard work, determination and pure Grit!
Adam and his team are exactly who you would want defending you in any situation. The absolute definition of hard work, grit and willingness.

Acted promptly, extremely happy, will continue to use in future.
Holborn Adams limited acted very promptly following our first meeting. Over all I was extremely happy with them and will contuine yo use them In The future
Best firm out there, like my guardian angels!
I had the unfortunate experience of being accused of something that I didn’t do, I had never had an issue with the police before and the whole experience was daunting and sent me to a dark place and I felt lost. In step Holborn Adams, my first contact was w

Adam Rasul is stand-up, trustworthy, driven, over-delivers, goes extra mile.
Adam Rasul is one of, if not the most stand-up and trustworthy people I've had the fortune to know or work with. I trust him implicitly with all matters and he has always over-delivered. Adam is utterly driven to provide the highest level of service and best o
Amazing team, professional, punctual, faultless attention to detail, fantastic work.
Holborn Adams are an amazing team to work with professional & punctual in every aspect of working together. The care & attention to detail is faultless & having experienced this high level of service for a number of years I would recommend Adam & his team to a

Brilliant job, great knowledge, successful outcome, professional, highly recommend.
Holborn Adams represented me for my criminal case,and what a brilliant job he done,along with he’s team. Holborn Adams dealt with my case with great knowledge and understanding. He took the time to get to know me and everything surrounding the case. To which w
Adam is an exceptional attorney whose expertise and commitment unparalleled.
I recently had the pleasure of working with Holborn Adams, and I cannot recommend them highly enough. From the very first consultation, it was clear that this firm operates with the utmost professionalism and dedication. The owner, Adam, is an exceptional at
Easily the best in the business, couldn't recommend enough.
I have used Holborn Adams multiple times for advice and assistance - easily the best in the business.The support they have given me in comparison to other firms is above and beyond. I couldn’t recommend these guys enough!!
Excellent service and well worth the fees.
Holborn Adams expertly helped my 15 year old son after he got caught up with a group of youths misbehaving and causing criminal damage in a high street store. The store chain wanted to press charges and the police pursued the whole group under group enterpris
Adam is exceptionally good and knowledgable, a true professional.
I cannot thank Adam and all the staff at Holborn Adams enough for the service they provided. Adam is a real credit to the profession. Not only is he exceptionally good and knowledgable at what he does but he is also a true professional. Would highly recommend
Exceptional legal services and advice, expert knowledge, calm professionalism.
⭐⭐⭐⭐⭐Holborn Adams Solicitors and, in particular, Adam Rasul have provided exceptional legal services and advice. We have successfully used Holborn Adams expertise to help our business in a number critical areas and their expert knowledge and calm professiona
Extremely professional and supportive, always contactable. Highly recommend their services.
Holborn Adams is helping me out with a legal matter at present and i cannot praise them highly enough. Holborn Adams has been extremely professional and supportive and is always contactable. I highly recommend their services
Adam is truly a pioneer in our industry.
I am very inspired by Holborn Adams work ethos, dedication, commitment and vision. In a short space of time he has turned his company Holborn Adams from a small business to a Leading 500 firm, being a Lawyer with a small business myself I know how difficult a
Expert representation with high standards driven from the top down.
Attention to detail and expert representation are the hallmark of this firm with high standards driven from the top down. If you are in legal trouble and you need to ensure the best service possible to produce the best outcome then look no further.
Fay Ashton showed me a different perspective of criminal defense.
My experience with Holborn Adams was absolutely positive! I had a false allegation made against me and was arrested. Being from a different country and not having any criminal background, I didn't know what my rights were and was given the option of having
Adam offers genuine personal service and unwavering commitment to clients.
We've known Adam and Holborn Adams for many years now. I've Seen his business grow based on providing results for his clients. Adam offers such a genuine personal service and unwavering commitment to do his best. For me it his his caring genuine approach which
Extremely thorough and pedantic, asking all the correct questions.
We had utilised the services of this firm. The strategy and tactics they deployed enable my family members case to be nipped in the bud at an early stage. Extremely thorough and pedantic, asking all the correct questions at the right time. All the ingredients
First-rate, pro-active, personal, supportive legal service. Highly recommended.
It’s so hard to know where to turn if you find yourself in the gut-wrenching position of needing specialist legal help. After extensive research of top law firms I chose Andrew & Ria at Holborn Adams because I thought that not only would they deliver a first-r
Adam showed great patience and empathy, offering great advice.
Having found myself in the situation where I needed to seek out some legal advice I knew there was only one team to contact. I went for the best as I needed the best. Adam showed great patience and empathy with me. Working alongside Andrew, they both offered
Fantastic service from Holborn Adams. Great professional service.
Received a fantastic service from Holborn Adams. Great professional service
Great help all the way through, highly recommend.
very Knowledgeable, great help all the way through. wish i had got Holborn Adams involved at the start and things would of not gone so far!. would highly recommend.Thanks for all your Help
Adams professionalism and knowledge shone through on court day.
I would like to first thank Adam Rasul and the team at Holborn Adams for assisting one of my most important clients on a very delicate case and I can only say Adams professionalism and knowledge shone through on court day and put myself and my client at great
Great patience and empathy shown by Adam and Andrew.
Having found myself in the situation where I needed to seek out some legal advice I knew there was only one team to contact. I went for the best as I needed the best.Adam showed great patience and empathy with me. Working alongside Andrew, they both offered
Highly approachable and efficient, represented me more than I did.
I was catered for in a kind and understanding way. I was not made to feel bad about my situation despite my own shortcomings and mistakes. I found Holborn Adams and Emily highly approachable and efficient. They represented me more than I did myself. The price
All about their clients. Leading pre charge since day one.
Holborn Adams 24/7 accessibility. All about their clients. World renowned for solicitors and pre charge. If you care about winning this is the firm to be. No legal aid. Pure private with a formidable reputation. Leading pre charge since day one, not just an ov
Great service, highly recommend Holborn Adams for support.
I received great service. I would highly recommend Holborn Adams for the service and support they provide.
Our Fees
Fixed fee defence
Our team will give you a free, no-obligation quote after your initial consultation. We offer a fixed fee service, free of any hidden extra costs. Our firm is exclusively privately-funded meaning we cannot accept any legal aid clients. Your fees secure you a top-tier team and top-tier treatment, covering
Dedicated, experienced legal team.
Ability to get your case dropped before charges.
Representation at interviews and court hearings.
Requests to vary bail conditions where required.
Negotiating with police or prosecutors
Referrals to various support services.

Frequently asked questions
Here are some answers to our most commonly asked questions - for tailored support with your case, please call us now for a free initial consultation.
Any attempt to mislead a lender, through false figures, a hidden debt, or an invented deposit source, to secure a mortgage or better terms falls within the offence. Prosecutors charge it under section 2 or section 3 of the Fraud Act 2006, with a maximum of 10 years in prison. Buy-to-let, residential, and remortgage applications all qualify.
Yes. Giving false details on a mortgage application can result in a fraud conviction, which carries a prison sentence of up to 10 years. Prosecutors must still prove dishonesty, and an honest mistake falls outside the offence.
The sentence depends on the amount involved and your level of culpability, with a maximum of 10 years in prison. The Sentencing Council fraud guideline sets the range, weighing the harm, measured mainly by the loss caused or intended, against culpability. A larger loss and a planned, sophisticated scheme push the sentence up, while a smaller loss and limited involvement bring it down. Outcomes range widely.
Lenders’ fraud teams and the police investigate, with specialist regional fraud teams or the National Crime Agency joining larger or linked cases. A report through Action Fraud often starts on the police side. Each route can begin with a letter, a request for documents, or an interview under caution.
Yes, if prosecutors prove that you personally acted dishonestly. Dishonesty must be proved for each person involved, so the broker’s conduct and yours are judged separately. Evidence that the broker completed the form alone can support your defence.
The marker is recorded against your name with Cifas, and other lenders, banks, and credit providers can see it, which can lead to refused mortgages, loans, and accounts. A lender records it when it suspects a false application. It typically stays on file for six years, even when the matter ends before charge. Early advice can test whether the lender had grounds to record it.
Yes, in some cases. After a conviction, the court can make a confiscation order under POCA for the benefit you gained from the offence, and that can include the mortgaged property. A restraint order can freeze the property even earlier, so advice on confiscation and asset restraint is critical.
Yes, we defend the full range of property fraud allegations, from false documents in a property sale to a purchase made in someone else's name. Take a sale where the paperwork says one thing and the facts say another: we go through every document line by line, so the Crown has to prove dishonesty rather than assume it.